
Canadian Mortgage Rate Forecast to 2028
Last updated:
The Bank of Canada is holding the line, and the latest bank forecasts suggest rates will stay higher for longer through 2027. Here is what buyers and owners ought to be doing now.
HIGHLIGHTS
The pause holds. The Bank of Canada kept its target overnight rate at 2.25 percent following improved economic and labour market conditions which reaffirm a broadening economic recovery, removing immediate pressure to cut rates.
A firming labour market. According to Statistics Canada and RBC Economics, Canada's labour market data firmed again in July 2026, removing the immediate pressure on the central bank to stimulate the economy.
Inflation and geopolitical risks. Total CPI sits at 3.0 percent, propped up by elevated energy prices due to the Middle East conflict and friction in the Strait of Hormuz.
Tariff headwinds. New US tariffs and Canadian counter-measures following the breakdown of bilateral trade negotiations pose fresh risks to growth while threatening to push costs higher over time.
Forecasts have shifted higher. Since our June update, the banks we survey have nudged their Bank of Canada forecasts up by less than a quarter of a percent through 2027, and the consensus now expects the next move to be a gradual increase. By early 2028, the outlook is unchanged from June. In short, rates are expected to stay higher for longer.
Fixed rates are heading higher. Variable rates have not moved since October 2025, and fixed rates have seen little movement since April 2025. Looking ahead, five-year bond yield forecasts are about a quarter of a percent higher through 2027, which pushes the fixed mortgage rate outlook up, especially over the next year. Variable rate forecasts are broadly unchanged.
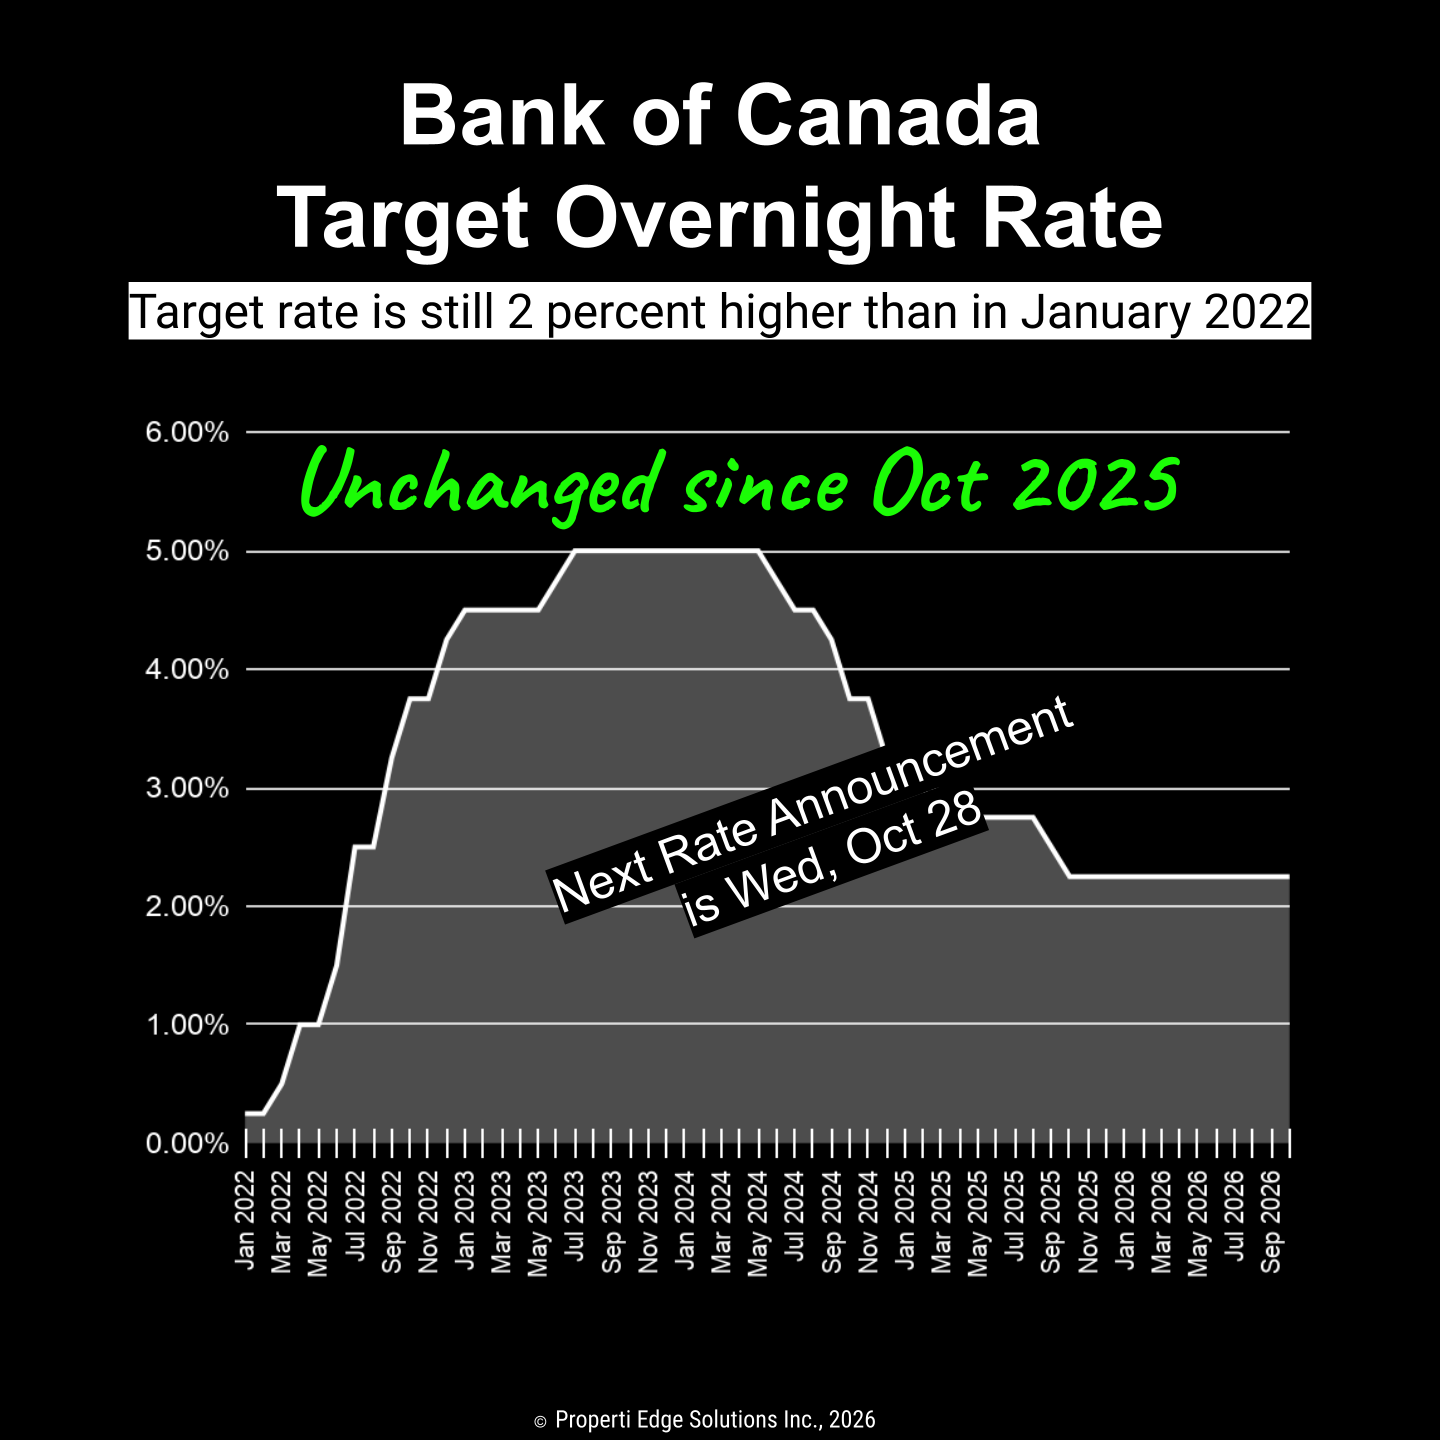
Bank of Canada Overnight Rate
Following a string of rate cuts in 2025, the Bank of Canada held its policy rate steady at 2.25 percent since October 2025. It was left unchanged again at their rate announcement on September 2, 2026. While economic growth has rebounded and labour conditions improved, the Governing Council noted that upside risks to inflation have increased due to the impact of the Iran War on energy prices and the effect of tariffs resulting from the Canada-U.S. trade war. All of this creates significant uncertainty. For Canadian borrowers, this confirms that rate cuts are paused as the central bank evaluates the sustainability of the current economic recovery. The latest bank forecasts go a step further: the consensus now expects the next move to be up, with the policy rate rising gradually by about half a percent by early 2028.
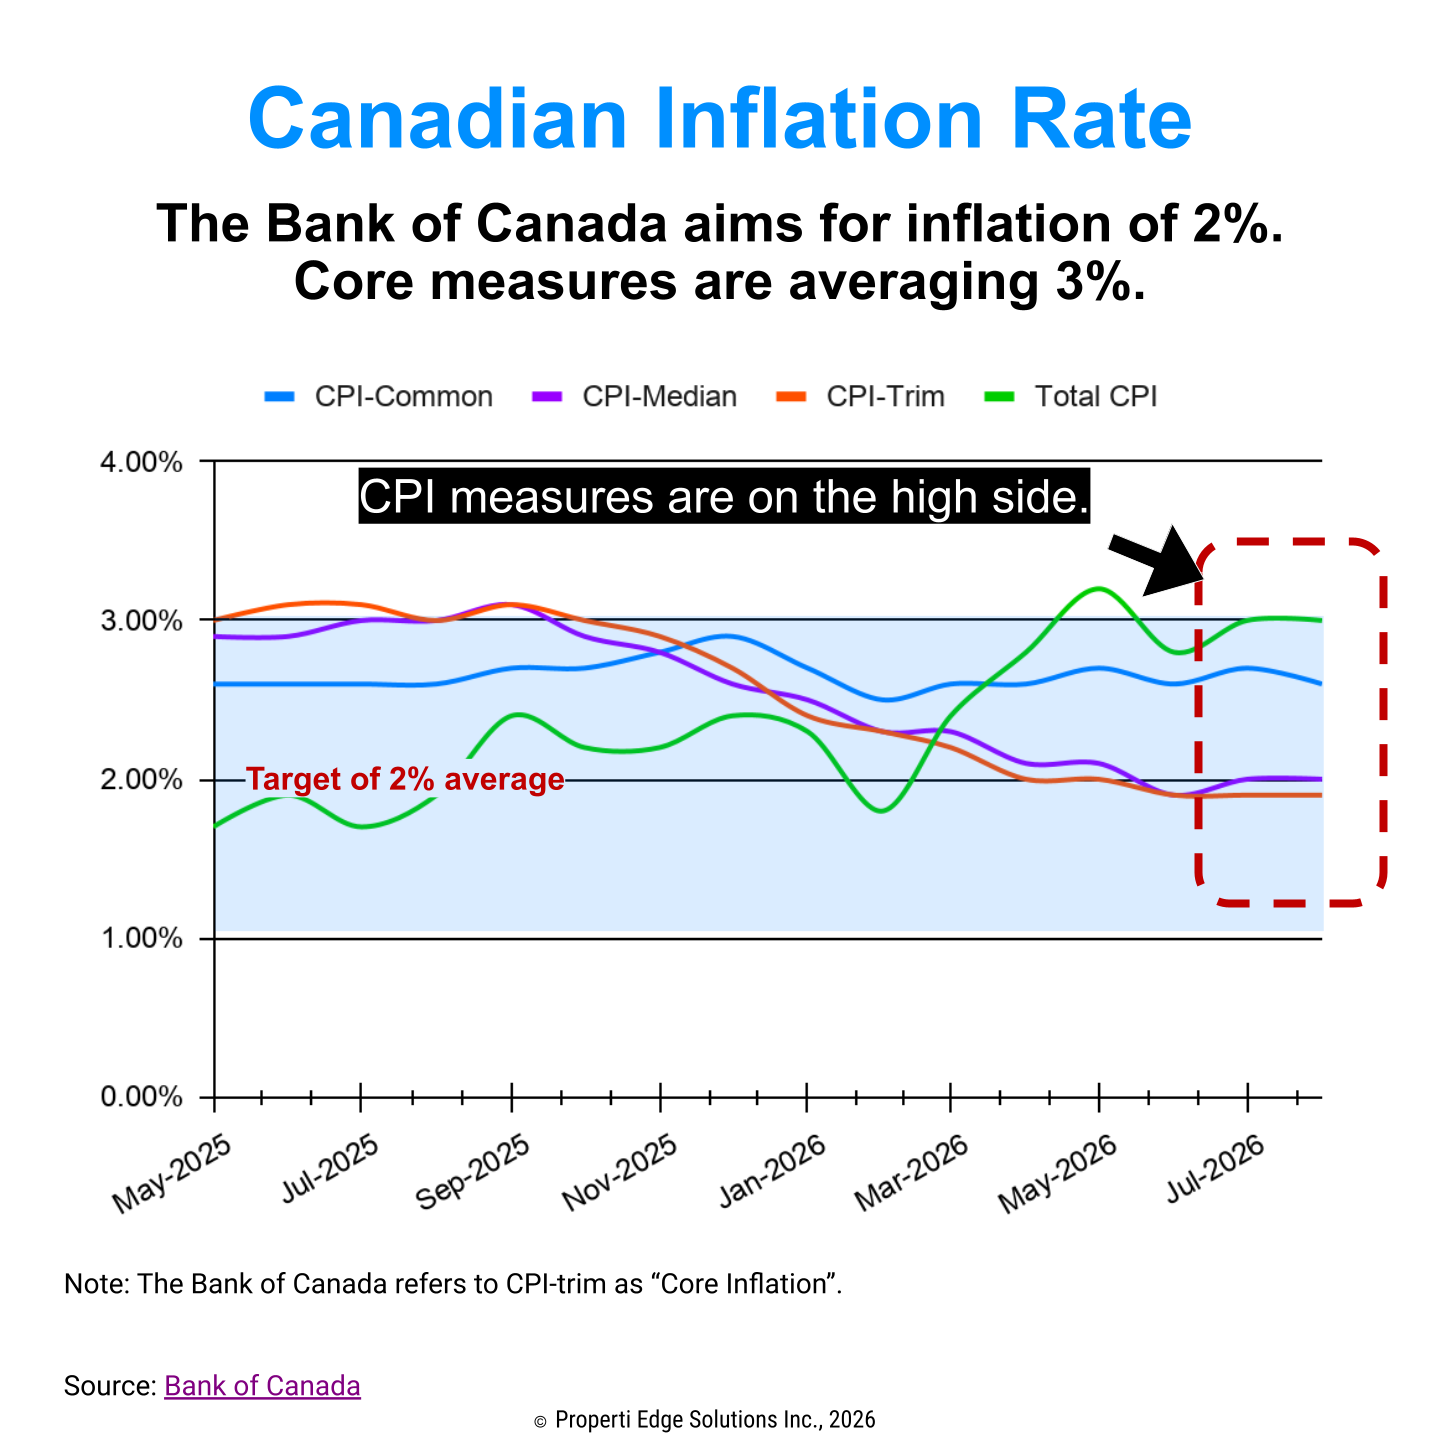
Fighting Inflation
Your mortgage rate in 2026 remains tethered to inflation.
Total inflation has hovered around 3.0 percent in recent months, largely driven by persistently high gasoline prices. Upside risks to the Bank’s inflation forecast have intensified due to the ongoing conflict in the Middle East and restricted transit through the Strait of Hormuz. Additionally, newly announced US tariffs and Canadian counter-tariffs threaten to raise business costs and feed directly into consumer prices over time.
Canada's Trade Diversification: Progress and Friction
Canada is actively reducing its ~70% reliance on U.S. exports through a multi-pronged diversification strategy: signing new trade deals (Indonesia, Ecuador, UAE; talks with India, ASEAN, Mercosur), expanding Indo-Pacific and EU ties, removing interprovincial barriers, and backing export infrastructure like port upgrades and the Trans Mountain pipeline. Early results are clear—non‑U.S. exports rose 11.1% in 2025 to hit a four‑decade high share (~one‑third of total).
Medium‑term structural shifts (3–7 years) will deepen as infrastructure and investment deals mature. The government’s target to double non‑U.S. exports by 2035 underscores that full reorientation is a decade‑long effort, with some analysts viewing it as a 15–50 year transformation on an accelerated clock.
In brief, diversifying Canada’s exports is not a quick fix.


The Bank of Canada Rate Forecast: A Pause, Then a Gradual Rise
The central bank is in a deliberate wait-and-see mode, judging the 2.25 percent target rate appropriate while monitoring market volatility. Although strong growth and improving employment diminish the need for monetary stimulus, the central bank warned that upside risks to inflation have increased. Governing Council remains prepared to adjust policy as needed to maintain price stability amid global upheaval and trade disruptions. Compared with our June update, the banks we survey have raised their Bank of Canada forecasts slightly, by less than a quarter of a percent for both late 2026 and mid-2027. By early 2028, the outlook is unchanged. In other words, forecasters expect rates to stay higher for longer rather than climb much further.
5-year Government Bonds
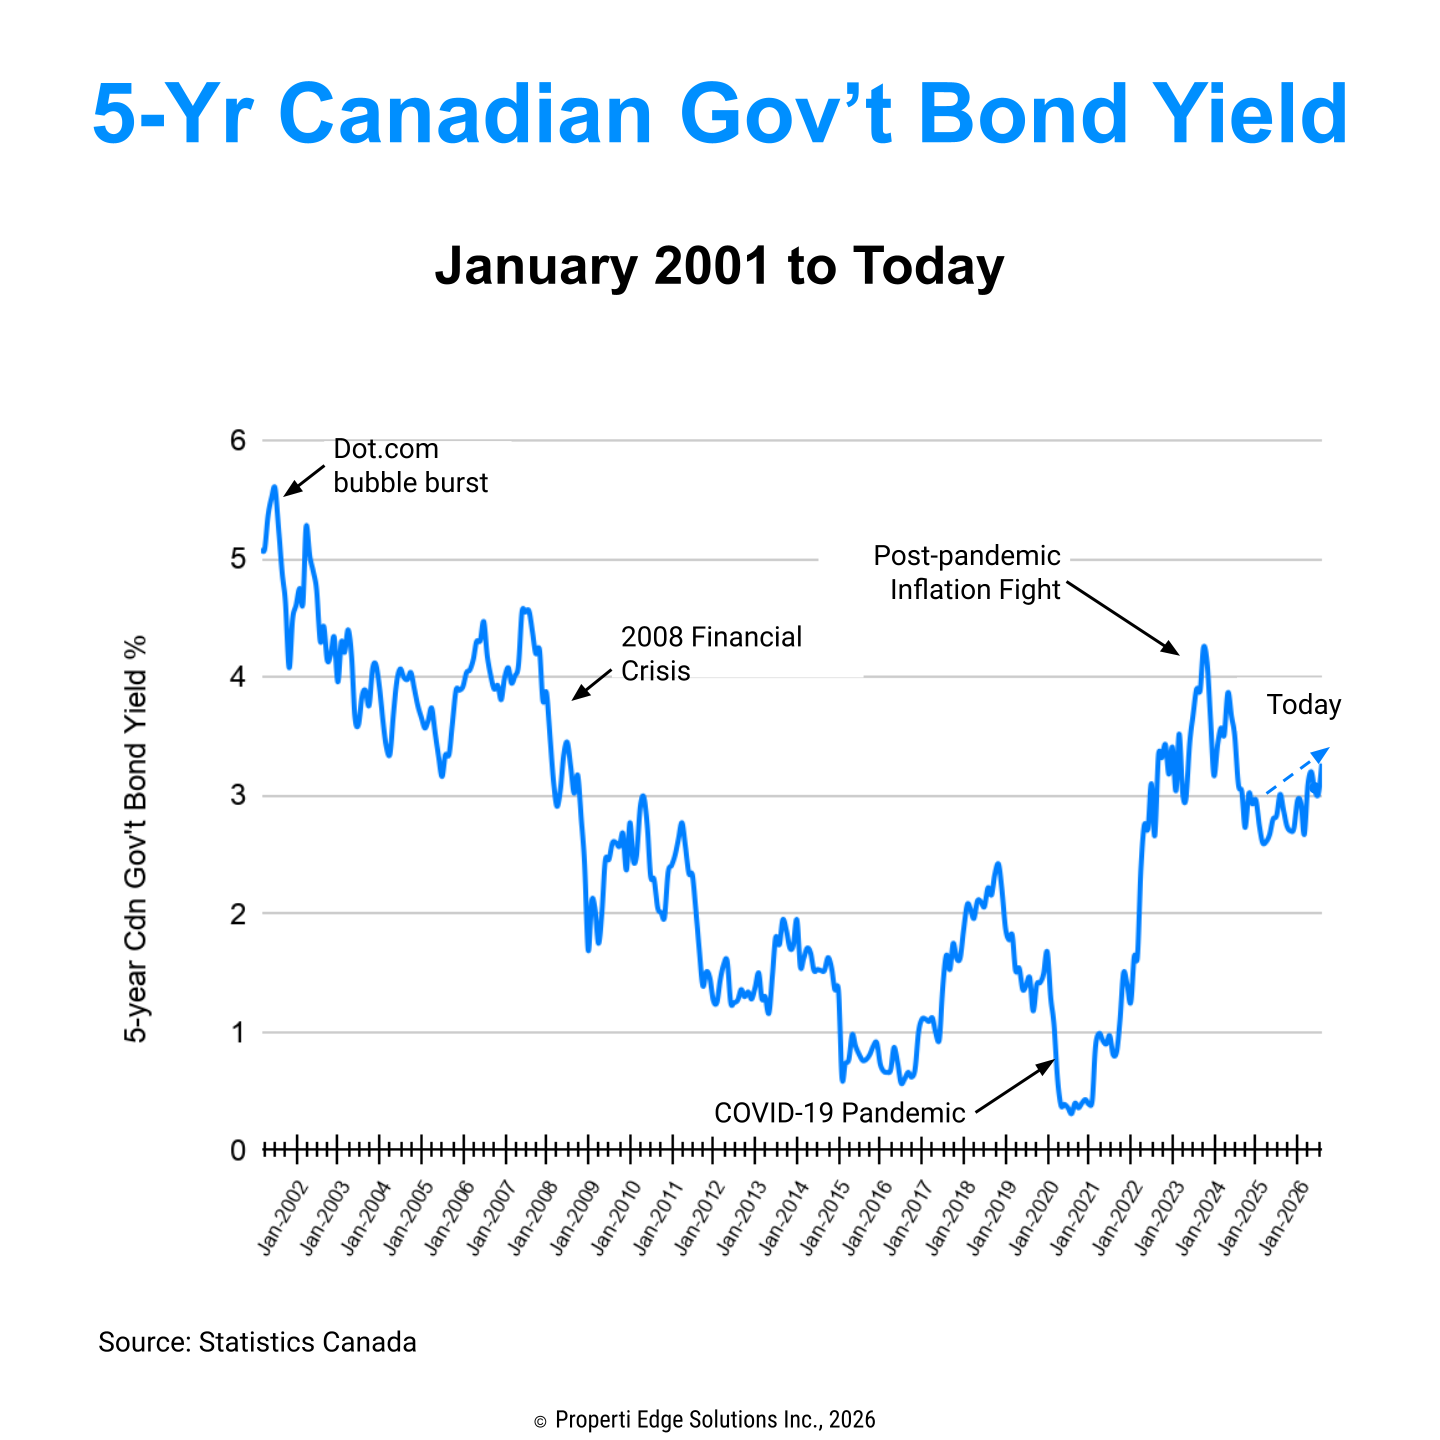
Fixed mortgage rates are closely bound to the yield on the five-year Government of Canada bond.
Yields on five-year Government of Canada bonds have moved upward, mirroring a global tightening of financial conditions. Persistent energy prices driven by Middle East supply disruptions, alongside newly enacted cross-border tariffs, continue to place upward pressure on bond yields and keep borrowing costs firm. Forecasts for the five-year bond yield are now about a quarter of a percent higher through 2027 than in our June update, which is the main reason our fixed mortgage rate outlook has moved up.
Sources
To build this analysis, we have surveyed the most prominent Canadian banks and their published forecasts.
Current Mortgage Rates in Canada
Recent Mortgage Rate Trends in Canada
While borrowing costs have fallen approximately 1.5 percentage points from their peak, rates remain elevated. Fixed mortgage rates are projected to drift higher over the next year, while variable rates are expected to hold near current levels, as markets absorb the impact of new trade tariffs and energy price volatility.

Fixed Mortgage Rates
Typical five-year fixed rates remain near 4.70 percent. With global bond yields trending higher and the Bank of Canada highlighting increased upside risks to inflation from energy prices and tariffs, fixed mortgage rates are more likely to rise than fall. Five-year bond yield forecasts are now about a quarter of a percent higher through 2027, so expect fixed rates to edge up, particularly over the next 12 months.

Variable Rates
Variable mortgage rates move in tandem with the Bank of Canada's prime-influencing policy rate. With the Bank confirming its rate hold at 2.25 percent, typical five-year variable rates remain steady at 4.00 percent. Our outlook for variable rates is broadly unchanged from June, and even slightly lower, because we now assume a slightly narrower spread between variable mortgage rates and the Bank of Canada rate.
Impact of Rates on Homebuyer Budgets
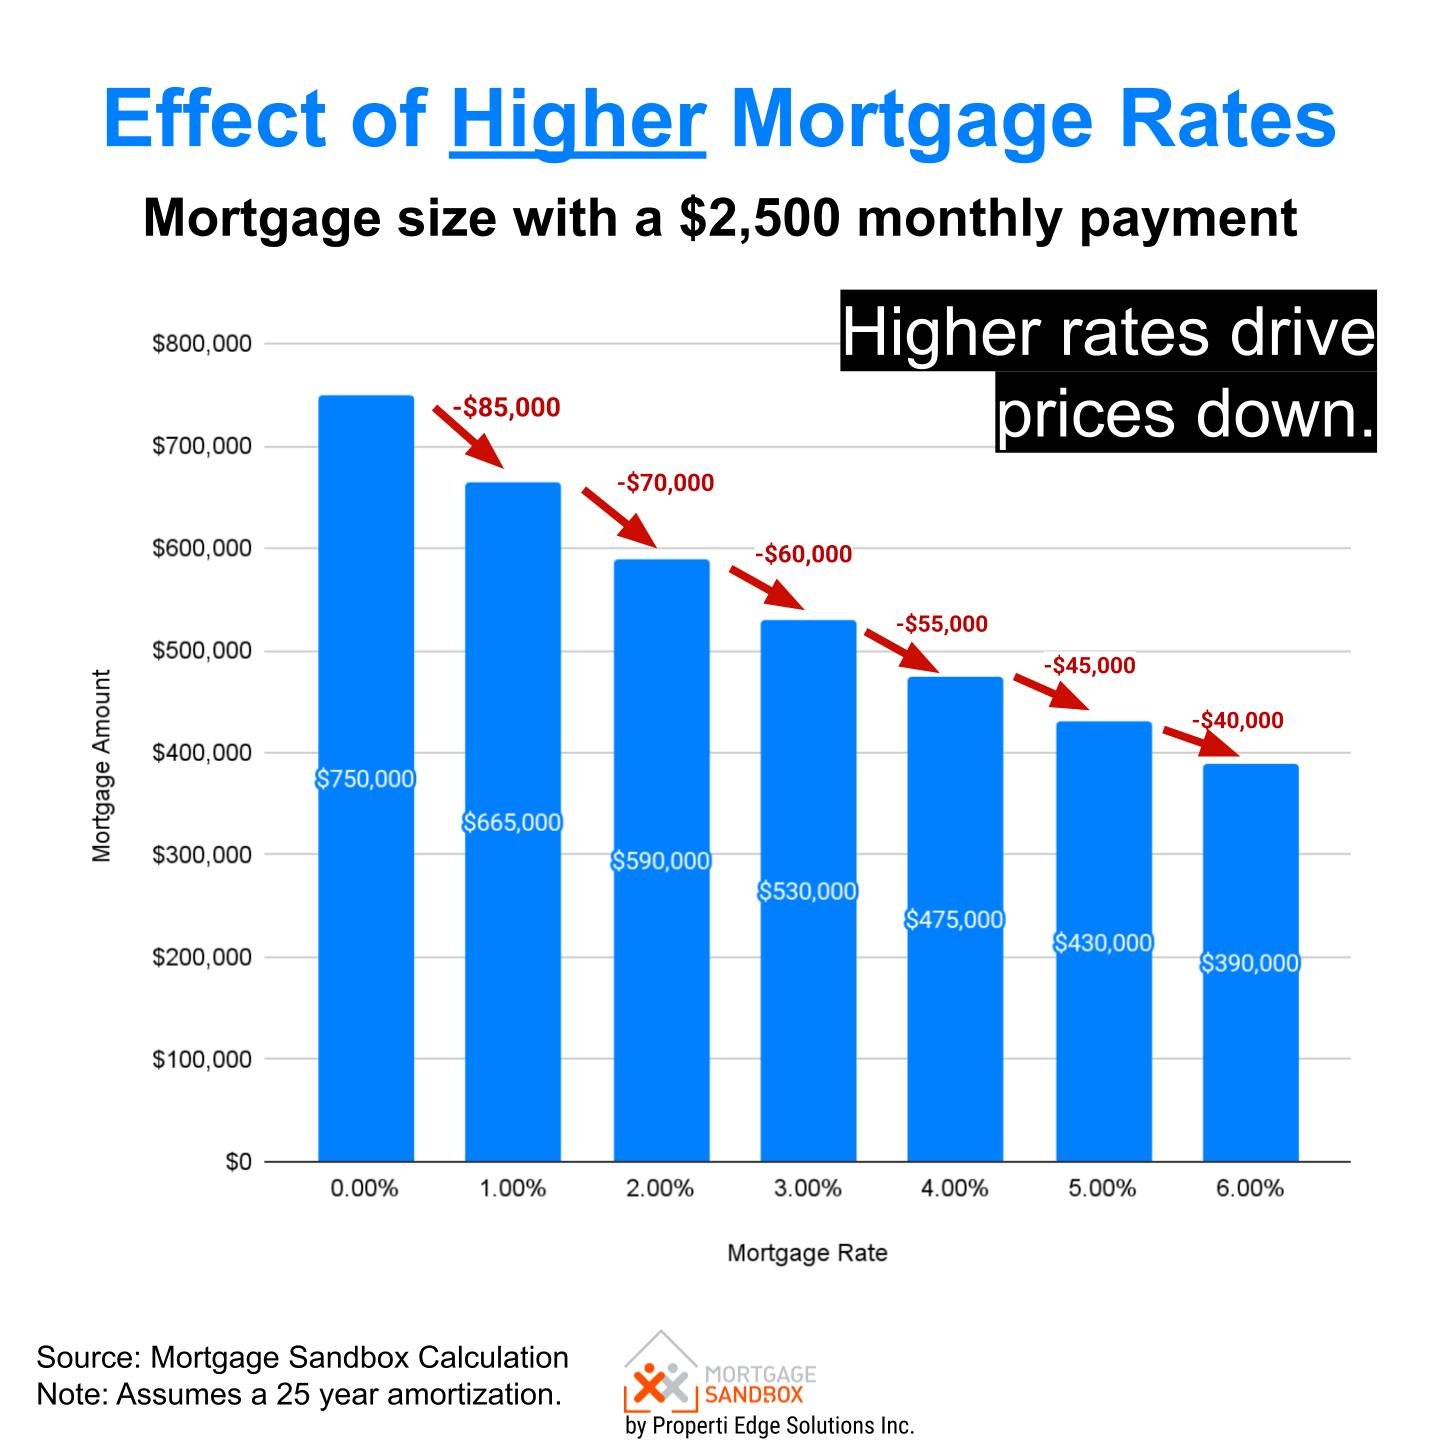
Impact of Rates on Homebuyer Budgets
A stable but elevated interest rate climate restricts purchasing power. Buyers must qualify at current stress-test levels, which limits the size of the loan they can secure. The result is a housing market where transactions take longer, and buyers must be highly disciplined with their budgets.
Need a mortgage refinance?Talk to one of our affiliated Mortgage Brokers Powered by Properti Edge |
Mortgage Rate Predictions Through 2028
Mortgage rates are projected to stay higher for longer through 2027. The latest bank forecasts point to fixed rates edging up in the near term and variable rates holding near current levels, with the outlook for early 2028 essentially unchanged from our June update. With new trade tariffs threatening higher input costs and the Middle East conflict sustaining elevated energy prices, central bank policy will stay cautious, and the next move by the Bank of Canada is more likely to be up than down. Rate reductions are considered very unlikely.
Will the 5 year fixed rate fall further?
A further drop in five-year fixed rates is unlikely under current conditions. Bond yields are reflecting persistent headline inflation, new trade tariffs, and elevated oil prices. Barring a sudden economic contraction that outweighs these inflationary pressures, fixed rates are more likely to rise than fall, with bond yield forecasts now about a quarter of a percent higher through 2027.
How much further will variable rates drop?
Variable rates have hit their floor for this cycle. The Bank of Canada’s decision to maintain the policy rate at 2.25 percent signals that additional rate cuts are off the table for the immediate future. Bank forecasts now lean toward the next move being up, though only gradually, by less than a quarter of a percent by the end of 2026. Because we now assume a slightly narrower spread between variable mortgage rates and the Bank of Canada rate, our variable rate outlook is broadly unchanged.
Try our mortgage offer comparison tool to calculate the dollar difference (not percent) between two offers. Find out how much cash you’ll save with a lower rate and the potential fees that come with different choices.
Fixed vs. Variable: Which is better now?
The case for fixed. A five-year fixed rate offers budget certainty and shields borrowers if persistent energy prices or cross-border tariffs trigger renewed inflation and lead to rate hikes. With fixed rates forecast to edge up over the next year, locking in sooner may cost less than waiting.
The case for variable. Variable rates offer a lower starting cost, but expose borrowers to risk if tariff-driven supply disruptions push rates higher.
A strategic middle ground. A three-year fixed term provides near-term stability while allowing borrowers to renegotiate once the long-term trade picture and energy supply pressures have stabilized.

Pros and cons of a 5-year fixed-rate mortgage
Pros include certainty of payments and protection from bond market volatility driven by U.S. trade or foreign policy.
Cons include higher penalties if you need to break the mortgage early, and you will not benefit if an unexpected recession forces the Bank to cut rates.
Not sure you've been offered a good renewal rate?Try our mortgage offer comparison tool Powered by Properti Edge |
Pros and cons of a variable rate mortgage
Pros include a lower starting rate and typically much lower penalties to break the contract.
Cons involve complete exposure to inflation and central bank policy. If trade bottlenecks push prices up, your borrowing costs could rise.
Not sure you've been offered a good deal?Try our mortgage offer comparison tool Powered by Properti Edge |
How to Get the Best Mortgage Rate
Start early and speak with an accredited mortgage broker 120 days before your renewal or closing date. Brokers negotiate on your behalf and can help you navigate the fine print, ensuring you get a mortgage that fits your lifestyle.
Further Reading: Our mortgage renewal guide that will help you navigate the process.
Is it a better time to buy or sell a home?
The higher-rate climate has balanced the market in many Canadian cities. Buyers have more time to inspect properties and negotiate, while sellers must rely on accurate pricing rather than the expectation of a bidding war.
Advice for Homebuyers
Your purchasing power is set by today's economic reality. Secure a pre-approval to hold a rate while you shop. Focus on homes you can comfortably afford instead of stretching your budget to the absolute maximum allowed by your lender.
Advice for Home Sellers:
Pricing your home correctly from the first day is essential. Work with a real estate professional who understands how current rates are impacting buyer budgets in your specific neighbourhood. Well-priced homes sell, while overpriced properties sit on the market.
Like this report? Like us on Facebook.
|
Do you have a financing strategy?Try our our Financing Strategy Explorer Powered by Properti Edge |
Canadian Real Estate Forecasts

Toronto
Real Estate Trends and Forecast

Montreal
Real Estate Trends and Forecast

Hamilton-Burlington
Real Estate Trends and forecast

Victoria
Real Estate Trends and Forecast

Vancouver
Real Estate Trends and Forecast

Ottawa
Real Estate Trends and forecast

Calgary
Real Estate Trends and Forecast

Edmonton
Real Estate Trends and Forecast
London, ON
Real Estate Trends and Forecast

Okanagan Valley
Real Estate Trends and Forecast
Like this report? Like us on Facebook.